Author: pippa@aurik.com

Recruit right people

HOW TO BUILD YOUR BUSINESS BY RECRUITING THE RIGHT PEOPLE TO DO THE RIGHT THING AT THE RIGHT TIME

As a small business owner, your biggest investment will be your staff. How you hire, who you hire, and when you hire, will have the biggest – positive or negative – effect on getting your business to the next level or not. On The Money Show with Bruce Whitfield, Pavlo Phitidis outlined his approach to getting recruitment right:

WHY ARE YOU HIRING SOMEONE?

Hiring people is an essential component of business growth. Without people, you don’t have a business. You have a job – that’s you doing it all, all the time.

Hiring people should be done to free your time from the tasks that consuming your time the most and that are teachable. The free time should see you move onto the next set of activities to build or grow your business. This is possible because you now have the time to do this. But only if that hire sees the right person coming on board doing the right thing at the right time. If not, you get drawn back into the time-consuming tasks you hoped to free yourself from and carry a higher cost of an unproductive hanger-on.

Some business owners hire people to save them or the business. They believe that the hire has the skills or insight needed to ‘fix’ the problem that they think is holding the business back. Getting this right is a relief. Mostly, however, it is a disappointment and an expensive one at that.

Because both hiring motivations are right, getting it right is vital making hiring a key competence of a business owner.

BEGIN WITH THE END IN MIND

Effective recruitment begins long before you begin advertising to fill a vacancy. Building a detailed job specification is just the start of the process. Your job specification should include: activities that you can to train someone to perform; activities that integrate with all the other activities that enable you to deliver a defined customer experience and, activities that are measurable. When drafting your job specification, think deeply about what your ideal candidates would be like – their background, demographics, skill sets, and attitudes.

DESIGN AND DISTRIBUTE THE OFFER

Once you’ve drafted the job specification and designed the salary package you’re ready to offer to the right candidate, it’s time to advertise the offer. Ask interested candidates to include a covering letter and CV. Including a list of requirements for the application process is an initial test of your potential candidates; if they’ve read your advertisement, engaged with the content, and supplied you with everything required, they’ve proven that they can attentively follow instructions. Anyone who doesn’t follow the somewhat simple requirements listed in your advertisement, can be immediately removed from your list of applications received.

SHORTLISTING AND BRIEFING

From all the applications, create your first shortlist of candidates that best fit your job specification. Select only those who have followed your instructions and shown an aptitude for the type of business you run. Ignore the lists of achievements on their CV and look more towards their attitude and practical abilities.

Then, invite your top 20 candidates to a briefing session. Prepare and share a presentation about your business, the job opportunity you’re offering, and the performance requirements. Invite questions and take note of the content of those questions, who asked them and their responses. That will give you great insight into the people on your shortlist and enable you to shortlist even further.

INVITE APPLICATIONS

After your presentation and Q&A session, ask your candidates to complete an application form for the job opportunity. Within this customised application form, be sure to ask questions that will help you to test understanding, temperament, skills and character. This application form process will help you to assess how your 20 candidates processed the information you shared with them, responded to it, and then communicate around it.

SHORTLIST AND INVITE CANDIDATES TO PITCH

From the applications that you received, select your top 5 candidates and invite them to individually pitch for the job opportunity. Look for who has thought through the opportunity best and has you and your business in mind rather than what they want. You want a hungry, passionate person who believes in the business and wants to be part of its future. From the pitches, select your top 2 candidates, and then conduct in-depth interviews with them. That’ll help you to assess and decide who your ideal staff member will be.

MEASURING PERFORMANCE

Measuring individual performance is imperative, as you build your business. Before you and your new hire commit to long-term employment within your business, implement a 3-month probation period, during which you’ll be able to assess their performance, and they’ll be able to assess how well they fit within your business.

Use your internal systems to measure performance and provide support to your new hire, as they settle into being part of how you build your business. All through the probation period, assess their performance and build their capacity and capability to perform at the job. If they hit the performance metrics during the probation period and get on with your team and culture, you probably have your winner!

Image source: https://bit.ly/2Nd8ogq
 

project revenues

ESCAPING THE PROJECT REVENUE TRAP

It’s an issue that faces any project or event-based business – they tend to generate bumpy revenues, which affects their ability to build momentum and secure growth funding. Listen to the podcast from The Money Show with Bruce Whitfield, as Pavlo Phitidis sets down a plan for business owners to escape the project-revenue trap!

WHAT IS A PROJECT DRIVEN REVENUE MODEL?

Any business that sells bespoke or customised work has a project-based revenue model. Examples include event management services to the supply of industrial plant and equipment. Securing deals like this are very appealing. They have lots of adrenalin and anticipation. It takes a real skill to win such deals because the value of these big deals is material. They can have some big numbers to them.

HOW DO THEY AFFECT THE TYPE OF BUSINESS YOU BUILD?

Depending on the type of product or service you sell, these deals require specialised skills. Typically, selling and securing a project, for example to build a piece of software to solve a problem or a massive mixing plant in an industrial bakery needs specialist skills. Specialist skills are by nature expensive. Often, the person with the skills is you, the business owner. You started the business because you had the skills to deliver this kind of product or service.

WHAT CHALLENGES DOES THIS KIND OF BUSINESS FACE?

There are numerous challenges including:

  1. Skills – access to specialist skills to ensure that you can sell, secure and deliver the project
  2. Bumpy revenue – its hard to secure reliable, predictable revenue. This makes building the business in an organised manner very hard. We refer to it as sine-wave-revenue. You spend your time chasing the deals because it requires your skill to secure them. Then, if you win them, you spend your time installing, delivering the product or service. in the meanwhile, there is no selling taking place unless you have a base of skills on board.
  3. Funding – its hard to secure funding n these types of businesses. Funders want and need reliable predictable revenue to service debt payments.
  4. Valuation – its hard to get a reliable valuation on these businesses. Valuation relies on free cashflow being generated over time. unpredictable revenues caused by the project nature of your revenue makes it hard to forecast a reliable estimate of the free cashflow.
  5. Sale – it’s a tough business to sell. A buyer would need to have your skills to see themselves buying and running the business.

ESCAPING THE PROJECT REVENUE TRAP

To move into a different revenue model, one that offers more certainty and predictability is a good idea. Such businesses build momentum, enable planning and growth in an organised way and over time yield very attractive valuations. They make for very attractive investments – hence the term Asset of Value.

Here are a few of the many strategies that you can deploy to make this shift in revenue model. However, beware, it’s a painful process and it take time. be sure you want to move there too because there will be some tough choices to make.

  1. Build products

Take a good look at all your projects. Identify the typical, most requested project. For example, if you are software developer, what is the most common problem that you find yourself building for clients. Correlate the projects against sector and industry. An important element of a product business is to have clear customer segment that you service and very well articulate problems that you solve. Create a workplan to begin building out the products. Try do this with a few of your client’s on-board right from the get-go. Allocate resources to this and deepen them over time. you will need a balance sheet to support this process. Those resources that serviced the project revenues are now going to service product revenues. These product revenues take time to build. Over time, as you deepen your product revenues, slowly switch the selling effort from project clients to product clients.

  1. Augment your projects

This is a far easy route to take. Think about the automotive industry. They started by selling cars. Once bought, that was it. today, they have added a suite of additional services. From motor-plans to driving experiences to trade-in deals, they have turned a once-off event into, in some cases, a revenue stream that lives as long as you might.

A client who supplied pumps as and when to mining customers took advantage of the recession and collapse in the mining industry to turn water elimination into a service. using technology and I.O.T he no longer sells pumps used to eliminate water form the shaft, but rather, sells a service that sees him being paid per hectolitre of water pumped.

  1. Deal make your volume

Because clients only buy as and when, look to deals that secure the as” right now and the “when” in the future. Its about selling to a client once and securing their further needs on other projects. For example, an eventing business could make a deal that offers a rebate on the future events if a client commits to 5 events in a year. do 10 such deals and you turn 10 projects with 10 clients into 50 projects in the year. the consistency of project acts to smooth your revenues.

These are some of the strategies we have developed for clients wanting to make the shift from project revenue to regular consistent revenues. Contact us and we’ll be sure to help you step beyond the project revenue trap.


time

Spend more time on your business and less time in it with improved business systems

We have seen a common theme emerging in our recent meetings with various entrepreneurs. As a business owner, you might be wondering how best to position yourself for the future amid South Africa’s junk status and unpredictable economy. You might be thinking about how to make the best of your business in this context, but also how you put yourself in the best position. You need your business to be a success without having to tire yourself out and being involved in the day-to-day operations. To be profitable, you must increase sales without spending more or allocating more resources. But isn’t there an easier or more efficient way of doing this than killing yourself by trying to be on top of every aspect of your business?

You are probably wearing yourself out thinking about how you can remain competitive and grow your business without having to spend so much time in the business to ensure things get done the right way at the right time…There must be a better way, there must be a system or example of someone else who has got this right.

The right stuff

To build a great business, you need to have a certain mindset and strategy that pertains to every aspect of your business, including business systems. Perhaps most importantly, have a plan in place that will bring your dream and vision to life. Make sure your plan is a bold vision for the future. You will have to spend a lot of time working on the ground, and having a vision will remind you of the end goal you are working towards. It’s important to keep an eye on the prize and be ready for the long haul. Learning from past failures equips business owners with the knowledge that is important for future decision-making and the experience will equip you with knowledge of the industry and deepen your relationships. And building on small successes will give you the confidence and momentum for the long haul.

We have the right tools

If you build your business on solid systems, you will be able to make use of the right technologies to automate your business systems. This will reduce your cost of delivery, increase your responsiveness and bring predictability to your service delivery. Technology (software and hardware) is cheaper now than ever and affordable for any business. The trick is to first build those systems manually and automate it in stages after this. The implementation of good business systems will result in business owners achieving scalable and sustainable growth across all areas of the company.

Don’t wear yourself out trying to do everything yourself, you might think you are busy driving the business but the business is driving you. Aurik has the tools for exhausted business owners to ensure scalable and sustainable business growth. If your business is systemised, you will drive it instead of it driving you.

positioning

POSITION YOUR BUSINESS FOR SUCCESS AND MAXIMUM IMPACT

Wing Chun Kung Fu, a style of martial arts, requires that you have a secure footing on the ground in all its defensive and offensive actions. This footing “anchors” you to the ground. It translates the force of your strike or block from your foot to your knees to your hips and torso to your strike or block. It lends integrity, strength and power to your action be it a kick or a punch.

Building and growing a business is no different. It all begins with positioning and leads all the effort and activity based on that positioning. Weak positioning or poorly articulated positioning will lead to misguided actions, investments, hires and decisions. It fragments and crumbles the businesses platform, leads to a life of chaos and frustrations as a #businessowner and will almost assure you a future where what you have built will never be saleable.

WHAT IS POSITIONING

This is all about what makes you special as a business. not in your view, but in the view of your customers. Not in what they say, as much as in what they do. that means, they say they like your service or product and they show it by returning again and again. They promote your business to friends and family. They turn their talk into walk.

WHY DOES IT MATTER

A well-built business that consistently gets to both the next level of growth and value is one that has been built of a clearly articulated, relevant positioning. It enjoys clarity and certainty in why it exists and how it will grow. Its “foot” is planted on the ground and points towards the direction that the strike or block needs to follow. The solid footing ensures that all the actions leading up to that strike are aligned, efficient and direct the maximum effort of the body’s movement into that strike.

These actions include marketing to generate leads, sales to convert those leads and operations to deliver the promise of the sales proposition. The team employed by the business understands how to work together, is well-coordinated and includes the right people doing the right thing at the right time.

A business that has no positioning or a poorly defined positioning can never direct and concentrate all its actions towards achieving its objectives. The actions would be fragmented and misaligned and the team would behave inconsistently and chaotically.

Poorly positioned business bleed effort, money and time since they are following an unstable footing.

WEAK POSITIONING STATEMENTS

When I ask most business owners what makes their business special, they say one of three things 99% of the time.

  1. Product – they argue the merits of their product in terms of its features and benefits. They might go so far as to say that their suppliers or manufacturing approach is unique and special. These aspects make their product superior. It’s the product that they have, hold and own or represent that makes them special.

The origins of this way of thinking date back to the mid-seventeen hundred when Ralph Waldo Emerson said, “build a better mousetrap and the world will beat a path to your door”. This is to say that a great product will always create a destination for customers to come to you. In the 18th century he was right. There were hardly any products around. Simply having one meant business!

  1. Service – many, in fact most, say it’s their service. that they offer personal service and will bend over backwards to accommodate and please their customers. Service wins the day and they offer that.
  2. Price – sometimes they argue price. Few argue that in fact because to attain price advantage over something in a competitive market is hard. If you are not in a competitive market, then price probably doesn’t matter in any event.

The fact is that seldom do any of these positions translate into a successful result.

Whilst each of these attributes may be true for a while, none remain true consistently. Money can build a better product, service is largely driven directly by the business owner (and that is not sustainable) and price advantage seldom lasts.

HOW DO YOU CREATE A WINNING POSITIONING?

Today, the world has become more fragmented and more individual than ever before in its trading history. IN 1922, Henry Ford produced the Model T Ford. He was quipped saying “you can have any model you want so long as it’s black”. Choices were limited then and more importantly, access to information and choice even more so. The trends today are focusing more on customised products and services than ever before and that is only going to increase.

In this world, spoilt for choice, customers want solutions to problems. These problems need to be lived, felt and experienced by the customers that a business serves. This means your positioning as a business needs to talk to the problems that you solve and who has them. If this is clear, then any marketing effort will contain messaging that resonates with the customers you want to reach. They will hear and identify with the problem that you claim to solve. Thereafter, any selling effort needs to demonstrate how your product or service will solve the problems you have articulated. Finally, the delivery of the product or service needs to create an experience that resonates with how customers, with the problems you have identified, want to be served.

It is the single most difficult thing to get right in a business. but when you do, all the actions that follow it will be aligned to generate momentum behind every investment and action you make in your business.

Working with Aurik, we revisit your positioning first. Once sure that it is relevant and clearly defined, we work with you to build all the actions your business needs to get to the next level of growth and value. Through this, we will ensure that you maximise your return on money, effort and time. Contact us today and let’s start the conversation.

the gap

Governance gets things done

Here is the story, titled “Whose Job Is It, Anyway?”

This is a story about four people named Everybody, Somebody, Anybody and Nobody. There was an important job to be done and Everybody was sure that Somebody would do it. Anybody could have done it, but Nobody did it. Somebody got angry about that because it was Everybody’s job. Everybody thought Anybody could do it, but Nobody realized that Everybody would not do it. It ended up that Everybody blamed Somebody when Nobody did what Anybody could have.

The story may be confusing, but the message is clear: no one took responsibility, so nothing got accomplished.

It is a story that plays out often in organisations and companies and on teams—anywhere there is culture that lacks accountability.

Without governance, which sounds like a reall corporate, unsexy word, nothing gets done, it is essential to have in place but so often we don’t see this in businesses – until it is too late. Listen the the podcast of Pavlo Phitidis discussing this on The Money Show on 702 and CapeTalk:


Why does it happen

There are several reasons and some more common but seldom understood examples include:

  • How we start is how we build and finish it. You may start out of necessity, which means there’s enormous pressure to get cash in, to sustain your existence. Often, the idea you start with isn’t what it ends up being. But you’re so busy banging away at it, you don’t see that there are cracks forming between partners.
  • Patterns in a relationship start shrouded in expectations not reality. Once set, they are hard to break. It feels ‘unfair’ to change the deliverables years after they were set.
  • Inexperience or ill-discipline. Often governance is only implemented when a business partner has been burnt by a lack of governance prior – very often the business would have failed because of it.
  • The busyness blur, fragments and mixes the hats – shareholders, board of directors and managing directors, but in a small business you are all three and they all get mixed into one.

Why do you need it?

  • Alignment between parties

Pulling in one direction builds momentum; its scientific P=M.V. D ideated by Descartes and calculated by Newton and now us on this call.

  • Decision making

There are around 120 decisions you take daily in a business; most are in your head and others are in your activities and work. Some are strategic, some are functional and in that some impact one function, some all functions. In many cases, being clear which hat, you are wearing when deciding a course of action is important. A shareholder disrupting a function is out of line. An operational director, alone taking a decision that impacts the company’s asset value is equally out of line…unless they are one and the same and alone in the business.

  • Accountability

Who does what by when and how? These are the things that make things happen. If everybody in the business is not guided by a set of activities, that can be measured, then how can you be sure that what needs to happen is happening when it needs to happen. For example, when you deliver a big job of work and someone else was meant to invoice; them failing to do so because they were not clear as to who was meant to invoice fails the business.

  • Play to strengths

Time is scarce and playing to your strength is vital to get the best impact most efficiently. I prefer partnerships because it gets that delivered but partnerships, ungoverned, are sinking ships.

How do you structure a governance framework?

  1. Recognize the 3 hats
  2. Understand their interests
  3. Determine across each domain, wearing the appropriate hat, roles, responsibilities, and actions aligned to the strategy of the business
  4. Shape remuneration to reflect the value
  5. Establish a delegation’s framework
  6. Reduce it to a set of agreements – shareholders and employment

It is of course easier said than done. Mostly, it requires a facilitated process by an objective, dispassionate, experienced third party. Get one and get it done to secure your future in time, money, relationship, self-worth, and value.

Black friday

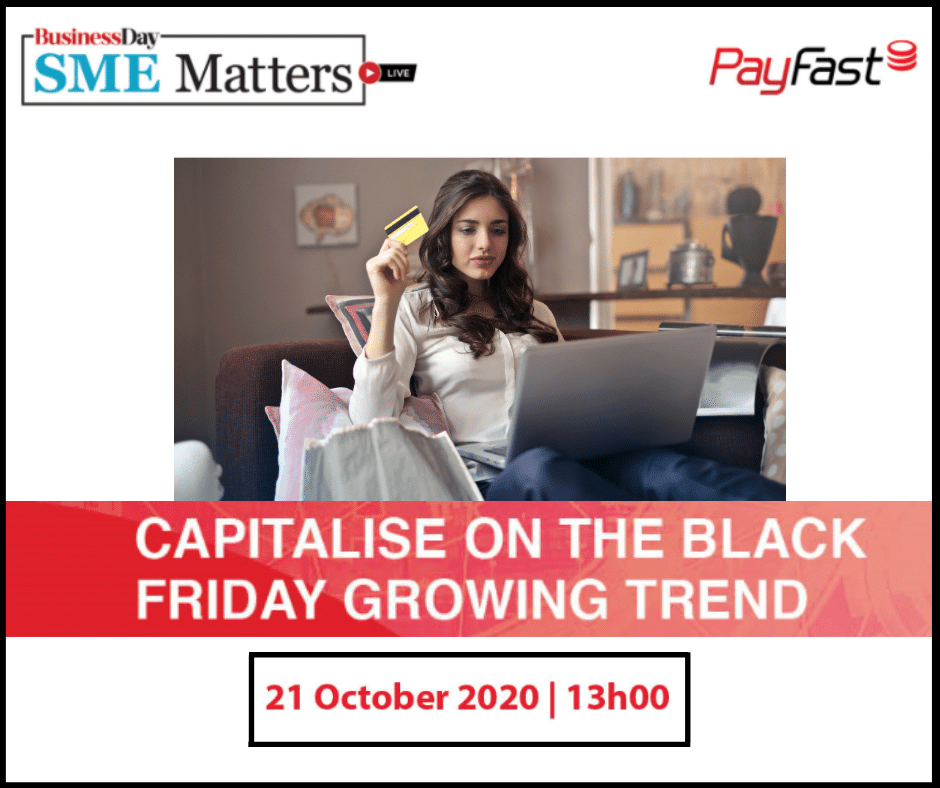
EVENT: Capitalise on Black Friday, no matter what business you are in

If there was an event that offered a spike in revenue to make up for losses over the last 6 months due to Covid-19, would you participate?

Black Friday and Cyber Monday are no longer the exclusive domain of TVs, toilet paper and a night’s stay in a hotel. Growth minded businesses across all industries are capitalising on these events and so should you too!

Join business growth specialist Pavlo Phitidis as he speaks to a panel of business owners on how to enable a digital offering, including a service offering, and how businesses can take advantage of e-commerce.

Date: 21 October 2020

Time: 13h00

Register HERE


engine

Build a sales engine not a sales team

Getting sales right is one of the most difficult tasks an entrepreneur faces, it is the ultimate testament of business understanding and sophistication.

Great salespeople don’t build a sustainable business – they do deals.

Pavlo chatted about the need to build a “selling engine” in your business on The Money Show . Listen to what he had to say here:

So what is a sales engine versus a sales team?

Things to consider:

1. A sales engine is bigger than a sales team and its more sustainable

2. Sales people walk in and out of the door daily, the engine if properly built is locked into the business

3. Horror stories

  • Lose the star sales person? And having no sales capability at all.
  • You pass on sales because you don’t like it! Not everyone is a natural sales person.
  • You build a channel driven business model!

4. Success stories

  • 97,8% of customers never met.
  • Break the sine wave

How do you build a Sales Engine?

You should always take the Asset of Value approach which means:

1. Turn the business to the customer

  • You can’t be everything to everyone
  • The better you define the customer, the better the alignment
  • It’s about solving customer problems not products

2. Understand the experience that customer wants to buy from you

3. Map out the activities that you need to create that generate that experience

4. This creates the selling system

5. Employ against that system

6. A clear job description is vital

7. Measurement of the system is vital

rough sea

Sailing blind in a storm will crash your business, generate, and use data to give you clarity of thought and action

Crises create chaos in a business. They also threaten a business’s existence. The stress generated from these events is profound and it wears you down to a place and space where you can give up hope and get destructive. If that is too dramatic, it can fray your nerves leaving you operating on raw emotion and impulse.

Both are terrible.

To take control back, you need a plan. Yet, a plan in a crisis is hard  to come by because often you are working with deep uncertainty. But there is a plan. It includes being able to change direction frequently until you stabilize the business and regain control. What tells you to change direction is where data becomes essential. Without it, you will work on impulse energized by either fear or a cavalier, destructive, all-or-nothing drive.

Listen to the podcast of Pavlo Phitidis’ discussion about creating and using data to make decisions in a crisis, from The Money Show on 702 and CapeTalk:

That is the conversation I had yesterday with a business owner.

Desperate for revenues and cashflow, he set his sales team out and into the wilderness. His instruction to them: Get whoever, however, whenever, anyhow, anyway, and anywhere…on board. We need sales.

He was right. They needed sales. How he wanted to get sales was the flaw in his plan. And it almost sunk him.

Strategy first

Stick to your knitting and remain focused on your value stack. Don’t ‘pivot’ without very careful consideration.

Run your numbers on the new offers you believe will sell in a crisis given the changes that your customers have and must undergo. Will these numbers help you to preserve your business?

System next

Set up a sales process and articulate the sales steps: what, why, who, when, where and how much?

A system is: Activities in a sequence that can be measured and taught. So identify the selling process, to deliver your changed offering, and the activities that make up the sales story.

Measurement

In short cycles (daily) measure the activities. When the deals don’t come in straight away, don’t recreate the whole process, go through the data of what, why, who, when where and how much to see where your customers are falling off and address that point.

Pick up the patterns of behavior of your customers through the sales process and tweak it to cater to the customers.

Do it with more than 1, or 5, or 10, or 20. You owe it to your team to have certainty and confidence that the offering and system works. They need to believe in it, to sell it.

Don’t do more and burn your relationships. If you apply it to all your customers, and it isn’t working, you undermine your social capital, and your team’s confidence.

Adjust

Make the changes in your sales process based on the data, and make only 1 change at a time and get it right.

Repeat the process and make subsequent changes, each time fixing or adjusting only 1 element of your sales process. This builds confidence in your team and creates a positive cycle.

Structure determines behavior

Once settled, and you have identified which customers and which offers are working, incentivise that behaviour in your team. It may be very different to the aggressive sales approach which won pre-Covid.

Why?

Time is not on your side, every action must count but while emotion clouds judgement, data keeps you sane. Act on data.

The seed of innovation and a reset business lies in a systematic approach to resolving a crisis. Not doing so could result in losing an opportunity to rebuild the business, relevant to your customers and as a result, reignite it to make up for lost revenues.

We are fallible and we are all prone to extreme emotions in a time of crisis. Seldom does an emotional knee-jerk or gutfeel in this environment result in a good, solid decision. Data clears the reliance on sight in a storm and reduces it to the cold, hard rational purview of a radar and GPS system. In a storm, as it will save your ship, in a crisis, it will save your business too.


bloody business

BUSINESS IS A BLOODY SPORT: WHY RISK MANAGEMENT IS IMPORTANT

In 2008, determined entrepreneur, Karabo Songo, established Olive Communications. I first met Karabo during the 2013 Business Accelerators radio segment, and was happy to discover that, by 2014, he’d followed through on the advice I’ve offered him. This led to him snapping up the deal of a lifetime – a large advertising contract with a corporate insurer. Karabo’s business grew, exponentially, from this, but then the problems began. In this podcast from The Money Show with Bruce Whitfield, we chatted to Karabo, touching on just how bloody the sport of business can get, and the importance of risk management:


Following Through on Advice

In 2013, Karabo sought to specialise his advertising agency’s services, and focus on serving a specific client segment. Selecting to serve the urban, black consumer market, Olive Communications quickly went on to win many accolades and scoop up some key client accounts. And then the deal of a lifetime came along: a corporate insurer who wanted Karabo and his team to lead their brand direction, transform internal marketing programmes, and secure the marketing chain supply. Karabo began to do just that, but then things started to go wrong.

The Bloody Sport of Building Businesses

Karabo’s re-engineered focus quickly spawned success for his client, as the insurer began to penetrate their chosen market with some success. But, a few months later, Karabo was notified that the services of Olive Communications were no longer required – a breach of contract that not only cost the company financially, but is also still tied up in legal proceedings. During that time, however, Karabo was approached by a global advertising group, who wished to buy Olive Communications and thereby establish their authority in understanding SA’s black consumer base. Agreeing to a 24-month acquisition strategy, this deal was structured as a BEE agreement, but problems soon appeared. As Karabo was treated more as a figurehead, rather than a partner, and often excluded from key operations, the relationship quickly soured. Moreover, within Olive Communications itself, members of the team were investing their energies into their own entities, and not focusing on the bigger business issues.

Transformation Deals – What do they mean?

Transformation is an agreed upon effort by both business and government that seeks to create access to skills and economic opportunities for previously disadvantaged individuals. Creating a more inclusive economy and business environment, the BEE codes and programmes seek to transform companies from within and through their supplier relationships. But some BEE deals don’t have the correct intention behind them. Big business, when looking to find partners or suppliers, should be selecting qualifying businesses that offer true value, innovation, and will actively contribute towards business growth, rather than just looking for a figurehead that’ll look good in corporate presentations. Secondly, policies and procedures must be implemented to ensure that standards are upheld and performance is assured. By that same token, small businesses must realise that being 100% black-owned isn’t a true value proposition on its own. Competition is strong in every sector, and building a well-functioning business that can – and does – truly deliver is critical.

Don’t Ignore Your Risk Management Needs

Landing the big deal is the big dream, but growing too quickly without managing your risk is perilous. Picking your deals carefully, and chasing the right ones, is important. A business grows through stages – one big deal does not make a successful business. In between each stage of growth, your business needs to pause, reflect upon lessons learnt, and then move on to its next stage of growth. In that way, a business is much like a small child – it must build muscle and grow, to carry its own weight. By ignoring your business’ need to grow in stages, you end up unable to deliver on what you need to. Building in stages helps you take care of your risk management needs.

Building and Sustaining Your Company Culture

Your company culture is a fundamental part of your business, and a clash of values will be catastrophic. Building your company culture, preserving it, and nurturing it, is key. But if there’s a difference of values or a culture clash between yourself and your clients and partners, you will have to build capacity to manage this, or walk away from a relationship before it destroys your company’s essence. Stay idealistic, focused, and preach your company’s mission, or else you’ll lose sight of the values that your business was founded upon in the first place. As Bruce says, culture eats strategy for breakfast.

Finding the right deals, rather than the big deals, is important for building a successful business. Chat to us at Aurik, and we’ll help you build your company into an asset of value.

digital marketing

WATCH: How to use digital marketing to drive sales and profits

In a noisy, crowded e-commerce environment, how do you get your brand to stand out to your potential customers? Which of the platforms work, and how much do you need to invest in content versus promotion? Pavlo Phitidis hosted a lively 60 minute discussion with three digital marketing experts, each with deep experience in Facebook, Google, LinkedIn as well as marketing strategy, to explore what works where and what is a waste of time for SMEs. Watch Pavlo, Musa Kalenga, Kath Sharfman and Aidan Baigrie debate the strategies and tactics that different size businesses should consider to use digital media effectively, and respond to viewers specific questions and challenges. The webinar was presented by Business Day SME Matters in partnership with Payfast and is part of a 4-part series. Follow the links at the bottom of the article for recordings of parts 1 and 2.


Part 1: Digital readiness: How to ready your business for the challenges and opportunities of the new world

Part 2: How to succeed in a crowded e-commerce space